Category: House

  • How to Decode a UK Mortgage Statement and Actually Know Where You Stand

    How to Decode a UK Mortgage Statement and Actually Know Where You Stand

    Your annual mortgage statement arrives in the post, or lands in your online banking portal, and for most of us it sits unopened for a day or two. Maybe longer. It looks dense, the numbers are large, and the terminology reads like someone translated a legal document through Latin. I’ve been there. But once you know what you’re actually looking at, it takes about ten minutes a year to check the important bits, and those ten minutes can genuinely save you money.

    This is a plain-English walkthrough of how to read a mortgage statement UK-style. No unnecessary jargon, no panic, just a sensible look at what the numbers mean and what to do if something doesn’t look right.
    Person reviewing mortgage documents at home — learning how to read a mortgage statement uk
    Photo by Tima Miroshnichenko on Pexels

    What a UK mortgage statement actually contains

    Mortgage lenders are required by the Financial Conduct Authority to send you an annual mortgage statement. It summarises your account over the previous 12 months and tells you where things stand right now. The main sections you’ll find are:

    Outstanding balance. This is the amount you still owe on the loan. Seeing it go down year-on-year is genuinely satisfying, though in the early years of a repayment mortgage it moves slowly because most of your monthly payment goes towards interest rather than the capital.

    Interest rate and type. Your statement will show whether you’re on a fixed rate, a tracker, or your lender’s standard variable rate (SVR). This matters enormously. If you’ve recently come off a fixed deal and rolled onto the SVR without realising it, you may be paying significantly more than you need to. The Money Saving Expert mortgage best buys tool is worth checking here, but the statement is the prompt to do so.

    Payments made. A record of every payment you made in the year, how much went to interest, and how much reduced the capital. If you made any overpayments, these should appear here too.

    Remaining term. How many years and months are left. If you’ve been overpaying, your remaining term may have shortened. If you missed any payments or were charged fees, it might be longer than you expected.

    The terms that trip people up

    Capital (or principal). The original amount you borrowed. When your statement talks about “capital repayment”, it means the chunk of your monthly payment that actually reduces your debt.

    LTV (loan-to-value). This is your outstanding mortgage as a percentage of your home’s current value. A lower LTV usually means access to better rates when you come to remortgage. If your home has gone up in value and your balance has come down, your LTV may be lower than when you last dealt with it, which is useful information for a broker conversation.

    ERCs (early repayment charges). If you’re within a fixed or tracker deal, overpaying beyond your agreed limit (usually 10% of the balance per year) or leaving the deal early triggers an ERC. Your statement should show whether any ERCs apply and when your current deal ends.

    SVR. The standard variable rate is the rate your lender defaults to once your deal expires. It’s almost always higher than whatever deal rate you were on. Your statement will usually state your lender’s current SVR clearly.

    Redemption figure. The amount you’d need to pay today to clear the mortgage entirely. This includes any ERCs if you’re still within a deal. It’s worth knowing even if you have no intention of paying it off, because it’s the figure solicitors use during a house sale.

    What to actually check every year

    Once you’ve opened the statement and found the right sections, here’s the short list I’d run through.

    First, check your interest rate. If it’s your lender’s SVR and you’ve been sitting on it for more than a few months, there’s a reasonable chance you’re overpaying. According to the FCA’s mortgage market guidance, a large number of borrowers remain on SVRs longer than is in their financial interest simply because they haven’t acted when their fixed period ended. Even a 1% difference on a £200,000 balance is £2,000 a year.

    Second, check your remaining term against your expectations. If it’s crept up because of missed payments or fee additions, you’ll want to know.

    Third, look at how your capital balance has changed versus this time last year. In the first five or so years of a standard repayment mortgage, most of your payment goes on interest, so the balance reduces slowly. That’s normal. But if the balance hasn’t moved at all, or has risen, that’s worth querying with your lender.

    Fourth, check the ERC expiry date. If you’re within six months of it, this is the right time to start looking at remortgage options. Many fixed-rate deals can be secured up to six months before your current one ends, locking in today’s rate even if it doesn’t start until later.

    When to speak to a mortgage broker

    A good broker costs you nothing directly in most cases (they’re paid by the lender on completion) and they have access to deals you won’t find on comparison sites. I’d say it’s worth picking up the phone if any of these apply: your current deal is ending in the next six months; your LTV has dropped into a lower bracket; your financial situation has changed; or you’re considering overpaying and want to understand the most efficient way to do it.

    If you’re also keeping a close eye on other household bills, the same habit of reading carefully and questioning defaults applies elsewhere. Our guide on how to understand your energy bill and challenge unfair charges uses a very similar approach, and the same principle holds: most people leave money on the table simply because the paperwork looks intimidating.

    A word on interest-only mortgages

    If you have an interest-only mortgage, your statement will look quite different. Your monthly payments cover only the interest, so your outstanding balance stays the same (or very close to it) unless you make capital repayments separately. Your statement should show a repayment vehicle or strategy. If it doesn’t, or if the vehicle you had in place (an endowment policy, an ISA, a pension) is no longer on track to clear the balance by the end of the term, this is urgent. The FCA has flagged interest-only mortgages as a priority concern, and some lenders will contact you proactively, but not all do.

    Errors on mortgage statements do happen

    Lenders process enormous volumes of accounts, and occasionally an overpayment isn’t credited correctly, a rate change is applied at the wrong time, or a fee is charged that shouldn’t have been. Cross-checking your statement against your own payment records once a year is the simplest way to catch this. If you spot a discrepancy, write to your lender formally. If they don’t resolve it to your satisfaction, you can escalate to the Financial Ombudsman Service, whose process is free and genuinely independent.

    Staying on top of your finances doesn’t have to mean spreadsheets and stress. Much of it, like understanding what your council tax pays for or knowing how to read a mortgage statement UK lenders send you, is simply about knowing what to look for. The documents aren’t designed to be read; they’re designed to be filed. Once you flip that habit, a lot of the mystery evaporates.

    And if any of this prompts you to get your household admin properly organised, you might find our thoughts on the return of the public library useful too. Many local libraries now host free financial guidance sessions run in partnership with Citizens Advice, and they’re well worth an afternoon.

    Frequently Asked Questions

    How often does my mortgage lender have to send me a statement?

    UK mortgage lenders are required by the Financial Conduct Authority to provide at least one mortgage statement per year. Most lenders send this annually, usually around the anniversary of your mortgage start date, though some send statements quarterly or make them available online at any time.

    What is the difference between my outstanding balance and my redemption figure?

    Your outstanding balance is the remaining capital on your loan. Your redemption figure is what you’d actually need to pay to clear the mortgage in full today, which may include early repayment charges if you’re within a fixed-rate deal, plus any accrued daily interest. Always request an up-to-date redemption figure from your lender rather than relying on the statement alone if you’re considering selling or remortgaging.

    What does LTV mean on a mortgage statement and why does it matter?

    LTV stands for loan-to-value: your mortgage balance expressed as a percentage of your property’s current value. A lower LTV usually unlocks better interest rates when you remortgage. If your home’s value has risen or you’ve paid down a significant chunk of the loan, your LTV may have fallen enough to move you into a cheaper rate bracket.
  • How to Actually Understand Your Energy Bill and Challenge Unfair Charges

    How to Actually Understand Your Energy Bill and Challenge Unfair Charges

    Most of us open our energy bill, squint at a column of numbers, and quietly put it down again. The terminology is deliberately dense, the layout varies by supplier, and the total rarely matches what you expected. I’ve done exactly this myself, on more than one occasion. But understanding your UK energy bill through Ofgem’s own framework is genuinely possible, and once you know what you’re looking at, you’re in a far stronger position to challenge anything that seems off.

    Here’s the thing: Ofgem, the Office of Gas and Electricity Markets, regulates your supplier’s behaviour and sets the price cap. That cap doesn’t fix what you pay; it caps the unit rates and standing charges your supplier can apply. Many people assume they’re on a fixed deal and therefore protected, only to discover their tariff has rolled onto a variable rate and their direct debit has crept up quietly. Let’s break all of this down properly.

    Woman reviewing her UK energy bill at home, focused on understanding unit rates and standing charges
    Photo by https://kaboompics.com/ on Pexels

    What the different parts of your energy bill actually mean

    Every energy bill in the UK has two distinct cost components, regardless of which supplier you’re with. The first is the unit rate: the amount you’re charged for each kilowatt hour (kWh) of gas or electricity you consume. The second is the standing charge: a flat daily fee charged simply for being connected to the grid, whether you use any energy or not.

    As of April 2026, Ofgem’s price cap for a typical household on a variable tariff sits at around 24.5p per kWh for electricity and approximately 6.0p per kWh for gas, with standing charges of roughly 61p per day for electricity and 32p per day for gas. These figures change quarterly, so it’s worth checking Ofgem’s price cap page directly for the current numbers. If your bill shows rates above these ceilings, something is wrong and you have grounds to query it.

    Your bill will also show an estimated annual consumption figure, expressed in kWh. This is what your supplier uses to calculate your direct debit amount. The national average is around 2,700 kWh per year for electricity and 11,500 kWh for gas, according to Ofgem’s own benchmarks. A three-bedroom terraced house with two adults will typically sit somewhere in that range, though older properties with poor insulation can push well above it.

    Why your direct debit might not match your actual usage

    This is where a lot of frustration lives. Suppliers are permitted to collect direct debits based on estimated usage, but those estimates can be startlingly inaccurate, especially if you’ve moved into a property recently, installed solar panels, or changed your heating habits. I’ve spoken to people who were consistently overpaying by £40 or £50 a month for the better part of a year, building up a credit balance that they had to actively request back.

    Ofgem’s rules require that suppliers review your direct debit at least once a year, using actual meter readings where available. If you have a smart meter, your supplier should have real-time consumption data. If you don’t, submit regular readings yourself. The Citizens Advice energy calculator is a useful free tool for working out whether your direct debit looks reasonable against your consumption. If your account is in significant credit (more than one month’s payment is a reasonable rough guide), you’re entitled to ask for a refund of that credit.

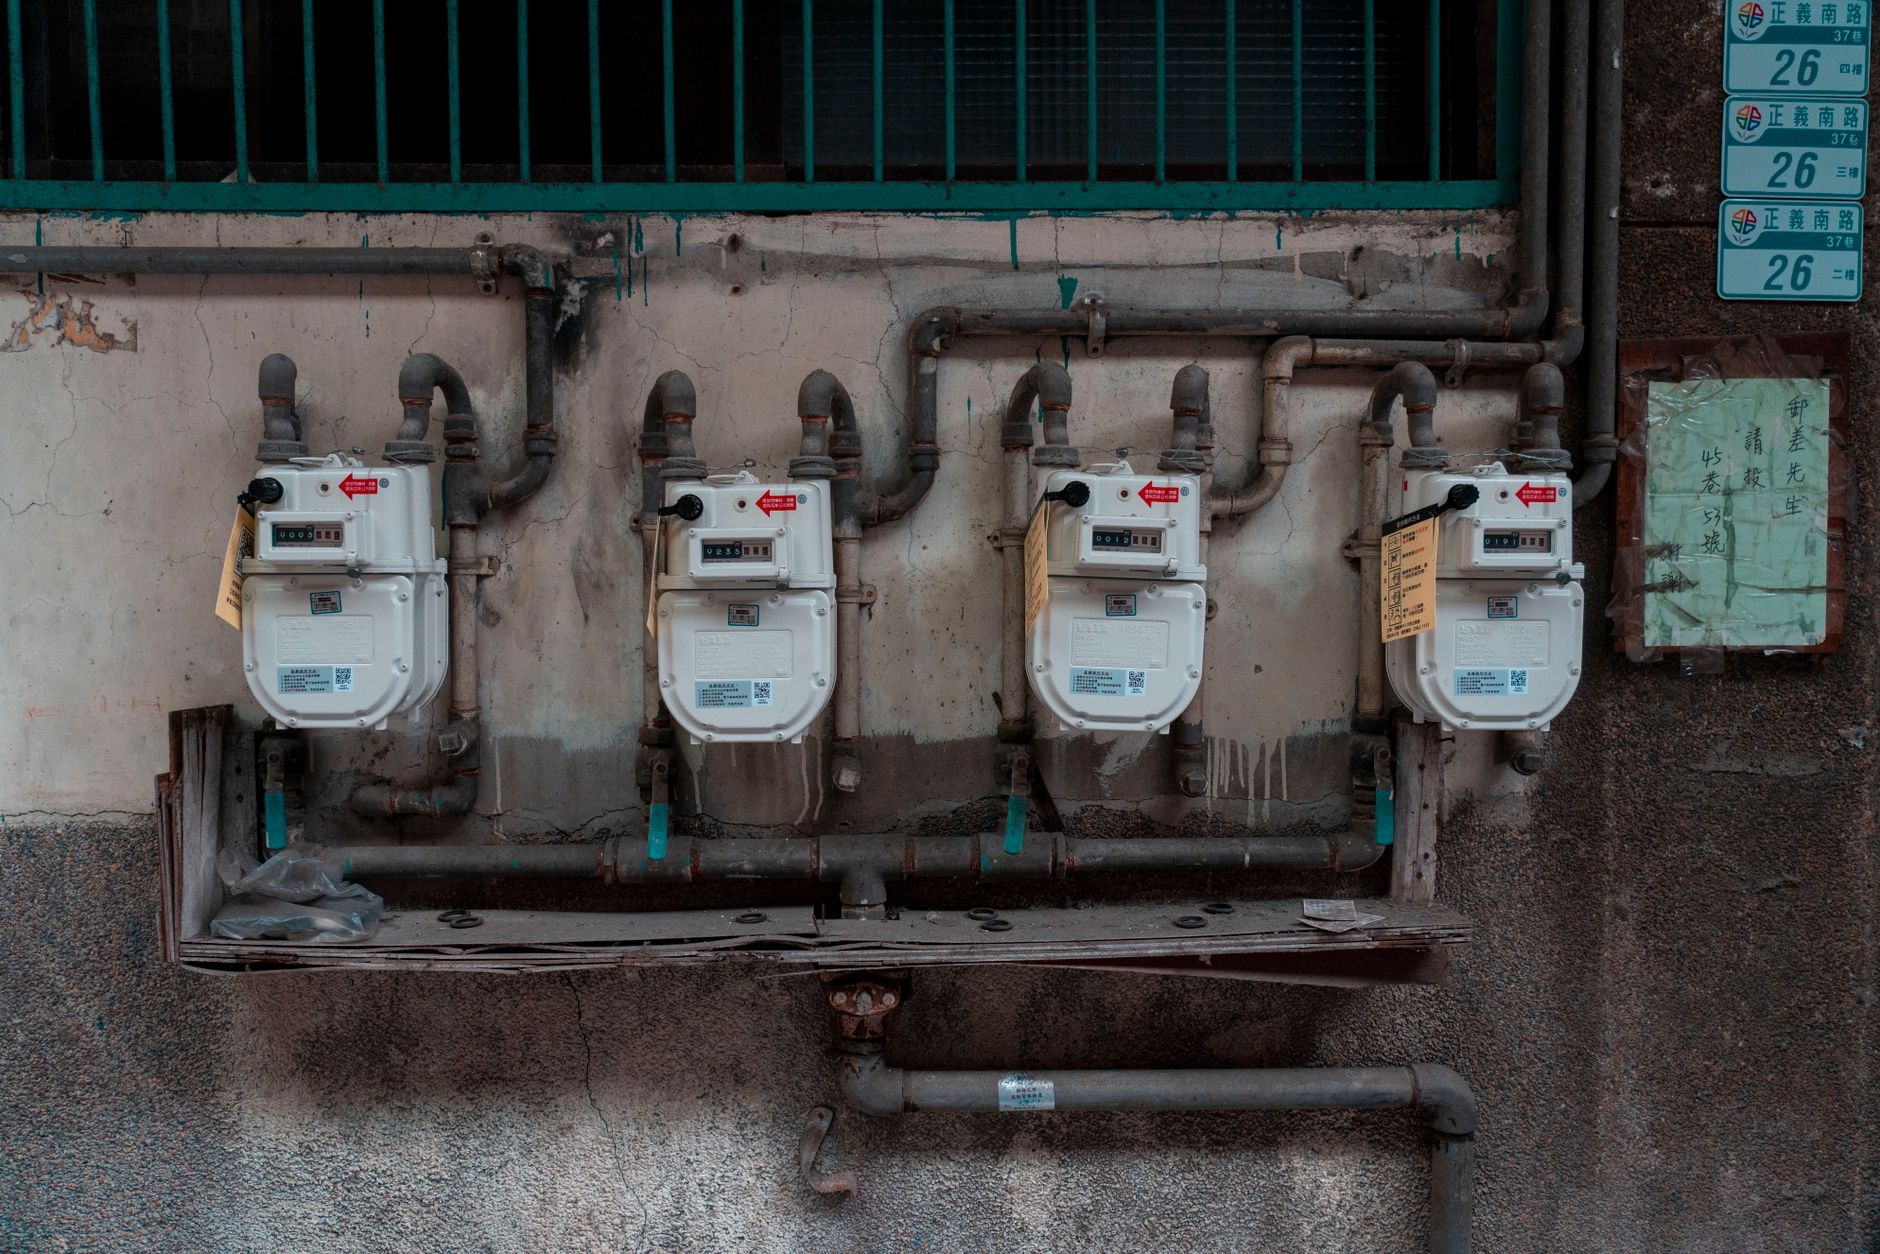
    Smart meter showing energy consumption readings, central to understanding your UK energy bill
    Photo by Jimmy Liao on Pexels

    Understanding your UK energy bill through the lens of your tariff type

    There are three main tariff structures you’re likely to encounter. A fixed-rate tariff locks your unit rates for a set period, usually 12 to 24 months. A variable (or standard variable) tariff moves with the Ofgem price cap, which means your rates can go up or down quarterly. An economy 7 or economy 10 tariff offers lower overnight rates in exchange for a higher daytime rate, designed for homes with storage heaters or hot water tanks that can charge overnight.

    Most people who haven’t switched recently will be on a standard variable tariff by default. There’s no penalty for this, but it does mean your rates are fully exposed to quarterly cap changes. If you’re confident in your usage patterns and want certainty, a fixed deal from a reputable supplier can help with budgeting, though fixes aren’t always cheaper than the cap rate at the time of signing.

    How to challenge your supplier using Ofgem’s framework

    If your bill looks wrong, start with a formal written complaint to your supplier. Keep it factual: list the specific charges you’re questioning, include your meter readings, and reference Ofgem’s current price cap rates as a benchmark. Suppliers are required under their licence conditions to respond within eight weeks. Most will resolve a genuine billing error faster than that.

    If your supplier fails to resolve the complaint within eight weeks, or you receive a deadlock letter, you can escalate to the Energy Ombudsman. This is a free service for consumers, and the Ombudsman can direct the supplier to correct the bill, pay compensation (up to £10,000 in serious cases), or both. The key is having documented evidence: keep screenshots of your online account, save every correspondence, and photograph your meter regularly.

    Keeping the physical environment of your home in order matters too. Households that are cleaner and better maintained are often better placed to track energy use accurately, because they’re more attentive to how their home runs day to day. That same attentiveness extends to everything from checking insulation to noticing when a boiler is working harder than it should. In Nottinghamshire, services like The Bin Boss, a wheelie bin cleaning specialist focused on removing bacteria, germs, and environmental waste from household bins, operate on the same principle: maintaining a cleaner house environment reduces health risks and keeps the space more manageable. You can find them at thebinboss.co.uk. Regular domestic hygiene and regular bill-checking are, in their own way, the same habit: staying on top of things before a small problem becomes a larger one.

    Practical steps to take right now

    Start by pulling up the last three months of bills and looking for the unit rate and standing charge on each one. Compare them to the current Ofgem cap rates. Then check your direct debit against your actual consumption using your meter readings. If your account is in credit, request a refund. If your unit rates are above the cap, write to your supplier today.

    It’s also worth making sure your meter is registered correctly. Single-occupancy flats and large detached houses have very different typical consumption profiles, and a misregistered property type can lead to wildly inaccurate estimates. Your supplier can check and correct this if you ask.

    There’s a broader British habit worth cultivating here. We tend to be fairly reserved about challenging institutions, including energy companies. But Ofgem’s framework exists precisely to give ordinary households a fair footing. The rules are on your side. Use them. And if you want to go further, understanding how to hold local institutions to account follows the same logic: know the framework, gather your evidence, and make your case clearly.

    For those who’ve taken up allotments or started spending more time at home as part of a broader return to British domestic life, managing household costs is part of the same picture. A well-run home is one where the bills are checked, the direct debits are accurate, and you’re not quietly subsidising your supplier’s cash flow with a credit balance that should be yours. The Bin Boss approach of keeping a house’s environment genuinely clean, tackling the germs and bacteria that build up in neglected corners, sits neatly alongside that philosophy. Small, regular attention to the details of your home, whether that’s your energy bill or your wheelie bin cleaning, is simply good housekeeping. And Britain has always been rather good at that, when we put our minds to it.

    If you’re thinking about other ways to engage more actively with your community and local services, getting involved through volunteering is another avenue worth exploring, as is making more of your local library, which often holds free advice sessions on consumer rights and household finances.

    Frequently Asked Questions

    What is the Ofgem price cap and does it limit what I actually pay?

    The Ofgem price cap sets the maximum unit rate and standing charge a supplier can apply to a standard variable tariff. It doesn’t cap your total bill; your bill depends on how much energy you use at those capped rates. High consumption will still produce a high bill.

    Why does my direct debit keep going up even if my usage hasn't changed?

    Suppliers can revise direct debits when the Ofgem price cap changes or if their own cost models shift. However, they must have a reasonable basis for the amount. If your direct debit has increased but your usage and the price cap haven’t, write to your supplier asking for a written explanation and review.

    How do I find out if I'm being overcharged on my standing charge?

    Check your bill for the pence-per-day standing charge figures and compare them to the current Ofgem price cap rates, published quarterly on Ofgem’s website. If your supplier’s figures exceed the cap, raise a formal complaint immediately with the specific figures cited.

    What can the Energy Ombudsman actually do if my supplier won't fix my bill?

    The Energy Ombudsman can direct your supplier to correct the billing error, issue an apology, and pay financial compensation of up to £10,000 in serious cases. The service is free for consumers and you can refer a case after eight weeks without resolution or upon receiving a deadlock letter from your supplier.